Mastering Financial Planning for Long-Term Caregiving
Discover essential strategies for financial planning to support long-term caregiving needs, ensuring stability and peace of mind.
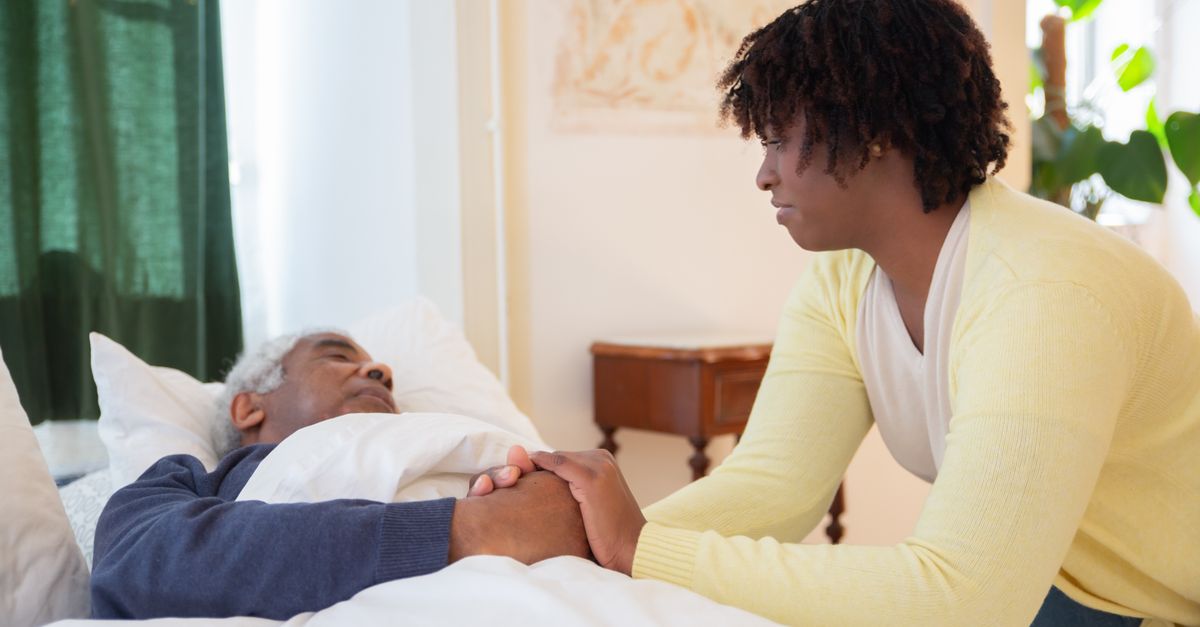
Caring for a loved one over the long term can be both rewarding and challenging. One of the most significant challenges is ensuring that there are adequate financial resources to sustain this care. Effective financial planning can help alleviate stress and allow caregivers to focus on providing the best possible care.
Understanding the Costs of Long-Term Care
Long-term caregiving can involve a variety of costs, many of which can escalate over time. These costs include medical expenses, home modifications, and professional caregiving services. According to the U.S. Department of Health and Human Services, the average cost for long-term care services can range significantly depending on the level and type of care required. Understanding these potential costs is vital for effective financial planning.
Assessing Personal Financial Resources
The first step in financial planning for long-term caregiving is to assess the current financial resources available. This includes savings, income from employment, retirement funds, and any other assets. Creating a detailed budget that accounts for monthly expenses and potential future costs can provide a clear picture of financial health and help identify any gaps in funding.
Exploring Insurance Options
Insurance can play a crucial role in covering the costs of long-term care. Long-term care insurance is specifically designed to cover services not typically covered by health insurance, Medicare, or Medicaid. It's essential to explore these options early, as premiums can increase with age and health conditions. Understanding what each policy covers and any limitations is crucial in choosing the right plan.
Government Programs and Benefits
Several government programs can offer financial assistance for long-term caregiving. Medicaid, for example, provides benefits for those with limited income and resources, covering certain long-term care services. Veterans may also be eligible for benefits through the Department of Veterans Affairs. It's important to research and apply for these programs as part of a comprehensive financial strategy.
Estate Planning and Legal Considerations
Estate planning ensures that a loved one’s financial affairs are in order, which can include setting up a durable power of attorney, establishing a will, and creating trusts. These legal documents can protect assets and ensure that the caregiver can make financial decisions on behalf of the care recipient if necessary. Consulting with a financial advisor or attorney can be beneficial in navigating these complex areas.
Creating a Contingency Plan
Even the best-laid plans can encounter unexpected challenges. Creating a contingency plan is an essential part of financial planning for long-term caregiving. This plan should include emergency funds, backup care options, and alternative financial strategies to ensure that care can continue uninterrupted.
Seeking Professional Financial Advice
Given the complexities involved in financial planning for long-term caregiving, seeking professional advice can be invaluable. Financial advisors can provide insights into investment strategies, tax implications, and potential cost-saving measures. They can also help caregivers navigate the emotional aspects of financial planning, ensuring that decisions are made with both financial and personal considerations in mind.
Regularly Reviewing and Adjusting the Plan
Financial planning is not a one-time event, especially when it comes to long-term caregiving. Regularly reviewing and adjusting the plan is crucial to accommodate changes in circumstances, such as shifts in health status, changes in available resources, or evolving care needs. Keeping the plan flexible and responsive can help ensure that caregiving remains sustainable over the long term.
In conclusion, financial planning for long-term caregiving requires a comprehensive approach that considers current resources, potential costs, and available assistance programs. By taking proactive steps and seeking professional guidance, caregivers can create a stable financial foundation that allows them to focus on what truly matters: providing quality care for their loved ones.